Consolidated Accounts Services
Understand the group as a whole. Bring parent and subsidiary figures together, with intercompany balances and reporting differences addressed in the agreed scope.
Consolidation support through associates for Malaysian SME groups. Start with your group structure and company records; agree the entities, reporting periods, currencies and outputs before preparation begins.
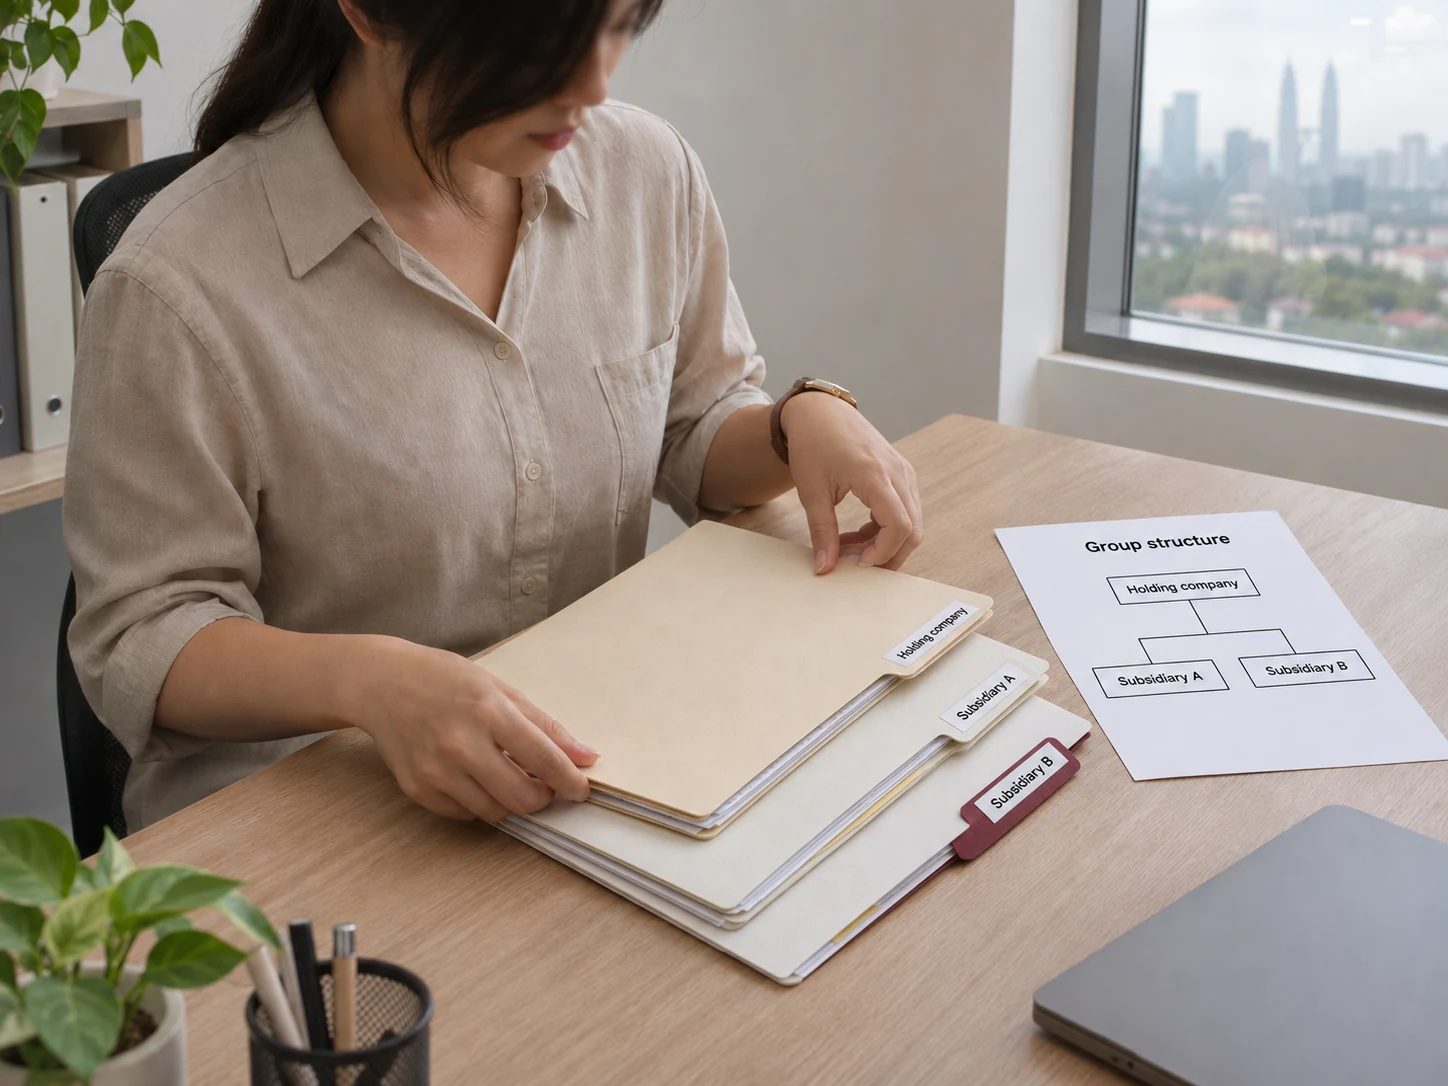
When a group needs one set of figures
Consolidation is for businesses made up of more than one company. You may need it if:
- your holding company has one or more subsidiaries and you need the group's results in one place
- your group has recently added a subsidiary and its records now need to be brought into the group's reporting
- your companies' balances with each other do not agree, and intercompany reconciliation keeps holding up the group figures
- you own several related companies and are not sure whether they form a "group" for accounting purposes
If you need day-to-day bookkeeping or accounting for each company rather than group figures, start with our accounting and bookkeeping services.
Do you need consolidated statements or an internal group view?
It depends on how your companies are linked and what you need the figures for. Consolidated financial statements are formal statements for a holding company and its subsidiaries, prepared under the approved accounting standards that apply to the group. An internal group view is management information for owners. It is not a set of consolidated financial statements.
Scroll sideways to see all columns.
| Topic | Consolidated financial statements | Internal group view |
|---|---|---|
| What it is | Annual statements that present a holding company and its subsidiaries as one group | A management view across related companies to help owners make decisions |
| How the companies are linked | A holding company and its subsidiaries, as the approved accounting standards that apply to the group define them | Companies with the same owners or managers, whether or not one owns the other |
| Who is responsible | The directors of the holding company | The owners and management |
| Status | Formal financial statements | Not a statutory document |
Whether your group is required to prepare consolidated financial statements depends on the accounting standards that apply to it. Your directors and advisers should confirm this for your group.
When you enquire, tell us which one you need. The associate confirms what the engagement will cover before any work starts.
What the consolidation work can cover
Consolidation support through associates works from the information each company in your group supplies:
- the group structure and ownership details you provide
- each company's source records for the period
- the reporting periods and currencies of the companies in the group
Depending on the agreed scope, the work can:
- organise balances and transactions between group companies
- align reporting periods, so each company's figures cover the right dates
- apply the group's agreed accounting policies, so similar items are treated the same way
- present the group figures agreed for the engagement
Each engagement names the associate doing the work, the person who reviews it and your contact. It also lists the outputs you will receive.
Define the group reporting scope clearly
Consolidation support does not include:
- audit, review or any other assurance work
- advice on mergers and acquisitions, valuations or purchase price work
- virtual CFO or business advisory services
If your group's statements need an audit, your separately engaged auditor carries it out.
How a consolidation engagement works
- STEP 01
Share the group structure
Tell us which companies are in the group, who owns what, each company's financial year-end and currency, and what you need the group figures for.
- STEP 02
Map each company's records
Review what each company can supply for the period, such as its trial balance and supporting records. Note any gaps and any balances between group companies that do not yet agree.
- STEP 03
Shape the working scope
Agree the companies, period, outputs, record-sharing method and timetable. The work is delivered through associates, and the scope names who carries it out and who reviews it.
- STEP 04
Prepare and review the group figures
Organise the balances between group companies, align reporting periods and apply the group's agreed accounting policies. Then review the agreed group figures with your named contact.
If one company's own records are behind, they usually need to be brought up to date before the group figures can be prepared. Catch-Up Bookkeeping & Accounts Clean-Up covers that work.
What shapes the fee for group accounts
There is no single public price for consolidation work. The discussion usually covers:
| What we assess | Why it affects the scope |
|---|---|
| Number of companies and levels in the group | Each company adds records to review and balances to match. |
| Currencies used across the group | Companies reporting in different currencies add to what the scope must cover. |
| Changes in ownership during the period | A company joining or leaving the group can add work. The scope confirms whether it is covered. |
| Volume of dealings between group companies | More intercompany transactions mean more balances to match. |
| Condition of each company's records | Late or incomplete records add work before consolidation can start. |
| Accounting standards and outputs required | The standards your group applies and the outputs you need shape the preparation work. |
The associate can explain the scope and fee after reviewing your group structure and records.
Common questions about consolidated accounts
What are non-controlling interests in consolidated financial statements?
Non-controlling interests are the equity in a subsidiary that is not attributable to the parent, directly or indirectly. For an ordinary shareholding, this represents the other shareholders' interest when the parent does not own all of the subsidiary. It is shown separately from the parent's owners' equity in the consolidated statement of financial position. Share the ownership percentages and any changes during the year so the associate can identify the relevant interests and reporting requirements.
What if group companies use different accounting systems?
Tell the associate which records and reports each system can provide, together with the reporting dates and currencies. The scope can then identify the information needed for the group figures and any gaps to address first. Software migration, system implementation or integration is not promised as part of consolidation.
How are intercompany transactions treated in consolidation?
Relevant balances and transactions within the group are eliminated in the consolidated group view under the applicable reporting framework. They must first be identified and reconciled before the agreed consolidation adjustments are prepared. Provide schedules from both companies and flag any differences. If a balance does not agree, supporting records are needed to understand the mismatch; unresolved items remain clear rather than being treated as automatically corrected or eliminated.
What exchange rate to use for consolidation?
There is not one exchange rate that can automatically be applied to every figure. The approach depends on each entity’s functional currency, the group’s presentation currency and the applicable reporting framework. IAS 21 distinguishes foreign-currency transactions from translating foreign operations and financial statements. Give the associate the currencies, periods and available exchange-rate information so the required treatment can be established for your group.
Which companies require consolidated financial statements?
The starting point is whether a company controls other entities, not simply whether several businesses share an owner. MIA’s guidance explains that a parent under MFRS must present consolidated financial statements, with control assessed under MFRS 10; MPERS has its own control assessment in Section 9. Your advisers should confirm the applicable framework and any exemption for your circumstances. Share the ownership and control structure when enquiring.
What are consolidated financial statements?
Consolidated financial statements present a parent and its subsidiaries as a single economic entity under the applicable reporting framework. They involve consolidation adjustments for transactions and balances within the group, rather than simply adding each company’s figures.
What is the difference between standalone and consolidated financial statements?
Standalone statements describe an individual entity. Consolidated statements present the parent and subsidiaries as one group, with consolidation adjustments rather than simply adding the separate figures. Which statements your group needs depends on the applicable framework and circumstances; share the group structure when enquiring.
How is the consolidation fee worked out?
The scope depends on the number of entities, ownership structure, record quality, intercompany activity, currencies and reporting periods. Share a group structure and the available accounts so the associate can assess the work before quoting.
How long will the group accounts take?
Timing depends on when each entity can provide usable accounts and supporting schedules, and how quickly intercompany differences and other questions are resolved. Share your reporting deadline early; the timetable is agreed after the group requirements are understood.
What are the limitations of consolidated financial statements?
A group report does not replace the information needed to assess a particular subsidiary’s own position or results. Review that company’s own figures alongside the group report when making company-specific decisions. Tell the associate whether you need group reporting, individual-company financial statements or both so the outputs are clear.
When should a subsidiary be consolidated?
Under MFRS, a subsidiary’s income and expenses enter the group statements from the date control is gained and remain included until control is lost. If a company joined or left your group during the year, provide the dates and supporting records instead of assuming its full year’s results belong in the consolidation. The associate needs these changes to confirm the reporting scope and applicable framework.
Is consolidation the same as an audit?
No. Consolidation brings the figures of group companies together into the agreed group figures. An audit is a separate engagement in which an auditor gives an opinion on financial statements. Audit is not part of this service. Any audit your group needs is carried out by an auditor it engages separately.
How to prepare a consolidated financial statement?
Begin with the group structure and each entity’s trial balance or accounts, reporting date, currency and accounting policies. Provide ownership details and schedules of transactions and balances between group companies. The applicable framework determines the consolidation adjustments. Differences need supporting evidence rather than automatic elimination, and the associate confirms the final records and scope for your group.
What if the subsidiaries have different financial year-ends?
This can happen, for example, when a company has recently joined a group. The Companies Act 2016 has rules on aligning financial years within a group, and those rules have exceptions, so your directors and advisers should confirm what applies to your group. Mention any different year-ends when you enquire, as they affect the scope.
Who is responsible for a group's consolidated financial statements?
The directors of the holding company. Responsibility for the group's financial statements stays with them, and outside help with the group figures does not move it away from them. Your directors and advisers should confirm the specific requirements that apply to your group.
Related accounting and bookkeeping services
Accounting & Bookkeeping
Explore ongoing bookkeeping, full-set accounts and the right reporting support for your business.
Management Accounts & Reporting
Regular internal reports that help owners and directors make decisions between annual statements.
Financial Statement Preparation
Statements for an individual company and the agreed period, prepared from complete supplied records. Those figures can feed into the group accounts.
Catch-Up Bookkeeping & Accounts Clean-Up
Bring historical or incomplete company records into a usable, reviewable state before group accounts are prepared.
Understand the records behind consolidated accounts
Prepare the group structure, each company’s accounts and the schedules for balances between companies before discussing your consolidation requirements.
What to prepare for your group accounts enquiry
Before you enquire, gather what you can:
- a chart of the group structure showing who owns what
- a list of the companies in the group, with each one's financial year-end and reporting currency
- the latest trial balance or accounts for each company
- a list of balances between group companies
- any consolidated statements prepared for earlier years
- details of any company that joined or left the group during the period
The final list depends on your group and the period. Share only records you are authorised to share, and never send passwords or system logins. The associate will explain what is needed next.
Discuss your group's accounts with TSE & Partners
Tell us how your group is structured, which period you need and whether you need formal consolidated statements or an internal group view. TSE & Partners PLT can then explain the consolidation support available through associates and the information needed next.